Who would gain, and who would pay, in a SpaceX-Tesla merger?
What would a SpaceX-Tesla merger mean for shareholders?
A potential shift in voting control. Musk directs the votes on about 17.7% of Tesla's shares today. In our illustration, SpaceX issues one-vote Class A shares for all of Tesla at the Nov 12 closing-price ratio, about 2.84 for one, with no premium and its share classes unchanged; on his disclosed holdings he would then direct about 75.6% of the combined company's nominal votes. Converted Tesla award shares are included in total votes but excluded from his directed votes; their voting treatment would depend on the terms (our calculation; figures from different dates). No terms have been announced. A deal would need Tesla shareholders' approval by a majority of all outstanding shares; two committees of independent directors are studying a combination, and Musk has said he is conflicted.
What it means
- What changed
- Both boards formed special committees in October, so a combination is under formal study; Bloomberg reported on Nov 12 that terms are being negotiated.
- What hasn't changed
- No agreement, exchange ratio or premium has been disclosed, and no transaction filing has been made.
- Next · Dec 8, 2026
- SpaceX's 180-day IPO lock-up ends, releasing more shares for sale; Musk's own lock-up runs to about June 2027.
Confirmed
- Both boards have formed special committees: SpaceX's to evaluate a combination with Tesla, Tesla's to explore 'deepening Tesla's relationship with SpaceX', possibly by a combination (third-quarter 10-Qs).
- No agreement has been announced. A SpaceX deal would need its committee, board and controlling shareholder; a Tesla deal its committee's recommendation and any necessary shareholder approval.
- Elon Musk held about 82.3% of SpaceX's votes after its June listing, through 10-vote Class B shares, and 19.8% of Tesla on its proxy's basis (SpaceX prospectus; Tesla proxy).
Not known
- Which company would buy which, at what exchange ratio, and whether Tesla's holders would get a premium.
- Whether Tesla would let its shareholders other than Musk decide on their own, through a 'majority of the minority' vote. None has been announced.
- Who sits on SpaceX's committee, which banks advise the committees, and when, or whether, they will report.
- SpaceX value, Nov 12
- $1.90T
- Tesla value, Nov 12
- $1.57T
- Musk's SpaceX votes
- ~82.3%
Prices: CNBC and Yahoo Finance historical close, Nov 13, 2026 · Company data: 10-Q, Sep 30, 2026 · What these numbers mean
Snapshot at the Nov 13, 2026 close
- Market value
- $1.54T
- Enterprise value
- $1.51T
- Price/sales
- 14.9×
- EV/sales
- 14.5×
- P/E
- 479.0×
- Price/FCF
- 467.0׆
- Revenue growth
- +8%
- FCF margin
- 3%†
- Net cash
- $35.7B
Our calculation from the company's filings (latest: 10-Q for the quarter to Sep 30, 2026, filed Oct 22, 2026); not investment advice. Revenue, earnings and cash flow: 12 months to Sep 30, 2026. Price $390.22 (CNBC and Yahoo Finance historical close); 3952.8 million shares (common shares on the cover page of the 10-Q filed Oct 22, 2026). n/m = not meaningful (e.g. negative earnings). † Free cash flow includes $1.3B of customer prepayments (increase in contract liabilities) in the 12 months to Sep 30, 2026.
Elon Musk runs two of the most valuable companies in the world, and both of them answer to public shareholders. Both boards have now formed special committees to explore combining them, putting a possible merger into a formal process. Musk, according to accounts of SpaceX’s October results call by Reuters and NPR, said a combination would be a good idea but that the decision belonged to the committees, because he is conflicted.
The question underneath is older than either company. When one founder’s businesses combine, who gains and who pays? Shareholders who own only Tesla, shareholders who bought SpaceX in June, the government agencies that depend on SpaceX’s rockets and the founder himself all start from different places. One consequence stands out: Musk directs the votes on about 17.7% of Tesla’s shares today, but in an all-stock deal that carried his 10-vote SpaceX shares into the combined company, he could hold about three-quarters of its votes (our illustration, with its assumptions, below). This explainer starts with what history says about putting businesses under one roof, then comes down to what has actually been said, who decides, how a price would be set, what stands in the way, and what each set of shareholders would be weighing.
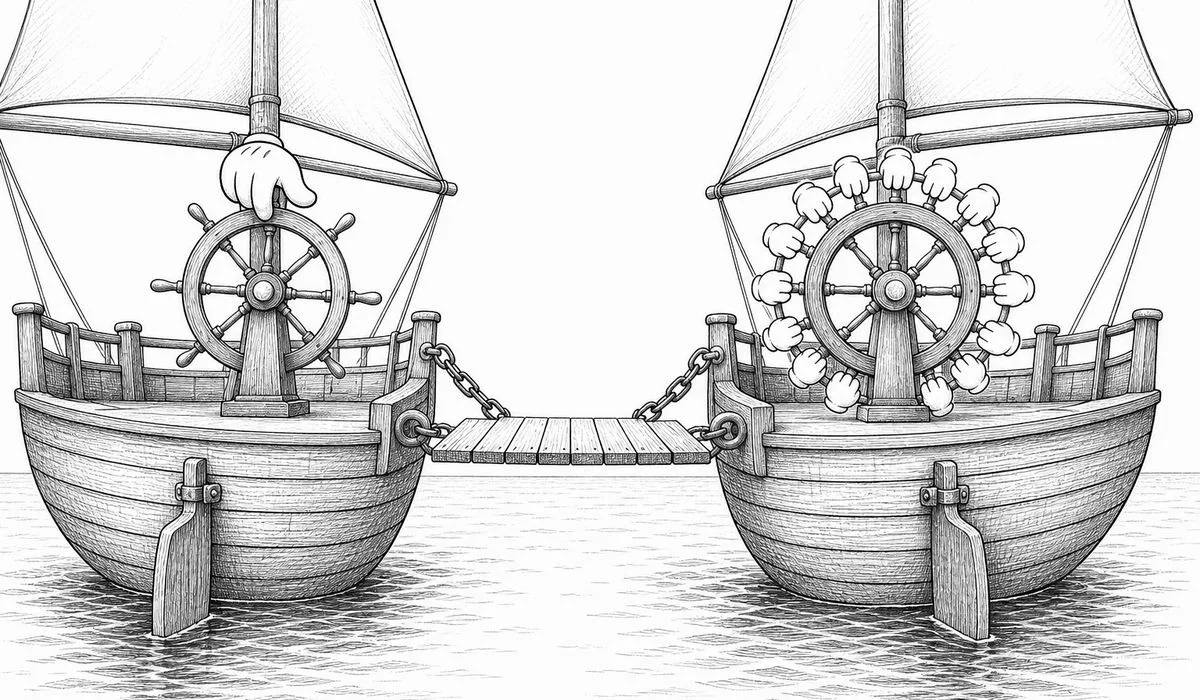
The question underneath: one roof, many owners
Investors have argued for decades over whether businesses are worth more together or apart. Economists Philip Berger and Eli Ofek studied 3,659 US companies from 1986 to 1991 and found that diversification was associated with lower value than comparable stand-alone businesses, a gap known as the conglomerate discount. Their study doesn’t establish what any single combination, including this one, would deliver. Warren Buffett, Berkshire Hathaway’s chairman, has argued both sides of it in one essay. “Conglomerates, it should be acknowledged, have a terrible reputation with investors,” he wrote in Berkshire’s 2014 annual report, published in 2015. “And they richly deserve it.” Yet, he went on, “if the conglomerate form is used judiciously, it is an ideal structure for maximizing long-term capital growth.”
Other companies have taken other paths. When Google reorganized into Alphabet in 2015, its co-founder Larry Page said “we think we can make it cleaner and more accountable,” and promised to report Google separately from the other businesses. General Electric, for a century the archetypal conglomerate, broke itself into three companies: GE HealthCare in January 2023, then GE Vernova in April 2024, leaving GE Aerospace.
None of these is a template for SpaceX and Tesla. Berkshire assembled businesses through acquisitions it controlled; Alphabet reorganized Google’s existing businesses; GE chose to separate. A SpaceX-Tesla deal would join two companies that are already public, with different owners and very different control structures, priced off two market values that move every day. The useful lesson is narrower: whether combining helps outside shareholders depends on who controls the combined company and on what terms, and that is exactly what the committees have to settle.
What has actually been said
On the record, there is less than the headlines suggest. In July, Musk said a combination couldn’t be discussed on an earnings call, Reuters reported; now both companies’ filings confirm that committees are studying it. SpaceX’s third-quarter report says its board formed a special committee “to evaluate a potential combination between SpaceX and Tesla,” that “no determination by our special committee has been made,” and that any deal “would be subject to further approval by our special committee, our board of directors and our controlling shareholder.” Tesla’s report describes a committee “comprising disinterested directors to explore deepening Tesla’s relationship with SpaceX, which could be through certain arrangements including without limitation a business combination,” subject to the committee’s recommendation and “any necessary shareholder approval.”
Beyond the filings, everything is reporting. Bloomberg reported on Nov 12, citing people familiar with the matter, that the boards and their advisers were negotiating terms and governance, and that an announcement could come in December or slip into early 2027. Reported accounts of Musk’s October remarks describe his support for a combination while stressing that terms may never be agreed. Neither company has confirmed Bloomberg’s account, and no merger agreement or transaction filing has been made.
Two companies, one founder, two kinds of control
The two companies look alike from a distance and very different up close. SpaceX listed its Class A shares on Nasdaq in June, selling 638.9 million shares at $135 for net proceeds of about $85.7 billion. Its Class B shares carry 10 votes each and elect a majority of the board, and after the listing Musk held about 82.3% of the votes. His ten-vote shares give him voting power well above his share of the company: his disclosed holdings equal 44.7% of the October share count, by our calculation, including roughly 1.3 billion shares that carry performance conditions. At Tesla every share has one vote. Musk owned 19.8% on the basis Tesla uses in its proxy, which leaves out 423.7 million award shares that are voted in proportion to the votes of all other Tesla shares, including Musk’s separately held shares; his own voting shares are about 17.7% of all shares outstanding, and about 28.4% including the awards.
Musk's share of the shares vs his share of the votes (%)
At SpaceX Musk holds 44.7% of the shares but about 82.3% of the votes; at Tesla he directs the votes on about 17.7% of the shares. In an illustrative all-stock deal at market prices with no premium, he would hold about 37.3% of the combined shares, including performance awards, and about 75.6% of the votes his holdings carry before counting the votes on converted Tesla awards, whose treatment is unknown.
VotesShares
Show the data table
| Measure | Percent |
|---|---|
| SpaceX: votes | 82.3 |
| SpaceX: shares | 44.7 |
| Tesla: votes he directs | 17.7 |
| Tesla: shares, with awards | 28.4 |
| Combined (illustration): votes | 75.6 |
| Combined (illustration): shares | 37.3 |
Since SpaceX’s listing on Jun 12, the gap between the two has swung widely. Using fixed October share counts, our reconstruction values SpaceX above Tesla on all 107 trading days through Nov 12, when SpaceX was worth about $1.90 trillion and Tesla about $1.57 trillion.
Market values of SpaceX and Tesla since SpaceX listed ($ trillions)
SpaceX has been valued above Tesla on every trading day since its June listing: from $2.19 trillion against $1.61 trillion on its first day, through a high of $2.74 trillion on Jun 16 and a low of $1.47 trillion on Aug 5, to $1.90 trillion against $1.57 trillion on Nov 12.
SpaceXTesla
Market value, $ trillions
Our calculation: daily closing price times a fixed share count, 13.58 billion SpaceX shares (Class A and B, both at the Class A price) and 3.95 billion Tesla shares, both as reported in the third-quarter 10-Qs; actual counts changed slightly over the period.
The two companies are already tied together. In February 2026 Musk’s xAI Holdings, which owns the AI developer xAI and the social network X, became a subsidiary of SpaceX. Tesla, after its shareholders’ advisory vote on investing in xAI failed in November 2025, put $2.00 billion into what became SpaceX shares in March. And SpaceX bought $480 million of Tesla’s Megapack batteries in the first nine months of 2026.
| Tie | What the filings say | Source |
|---|---|---|
| xAI and X inside SpaceX | xAI Holdings “became a subsidiary of SpaceX in February 2026” | Tesla proxy |
| Tesla’s stake in SpaceX | A $2.00 billion investment completed Mar 12, 2026, under 1% | Tesla 10-Q and proxy |
| SpaceX buying from Tesla | $480 million of Megapacks in the first nine months of 2026 | SpaceX 10-Q |
| Shared chief executive | Musk is chief executive of both | Both companies’ filings |
Who decides, and how
The first decision belongs to the committees. Neither company has named its committee’s financial advisers or said whether it will obtain a fairness opinion, the bank’s judgment that a price is fair to the shareholders it represents, though in deals of this kind each side usually does.
Then come the votes, and here the two companies differ sharply. Tesla, now a Texas corporation, requires a majority of all its outstanding shares to approve a “fundamental business transaction” such as a merger. Musk’s shares would count toward that majority, so the deal would still need broad support from other holders: if every share voted, with Tesla’s 423.7 million award shares voted in proportion to the rest, it would need about 1.065 billion yes votes besides Musk’s 699.6 million, or 26.9% of shares outstanding (our calculation). The committees could also add a separate condition, a vote of the shareholders other than Musk, known as a “majority of the minority.” None has been announced. At SpaceX, approval rests effectively with Musk: with about 82.3% of the votes, he could carry any shareholder approval the deal needed.
Tesla has done this before, under different rules. In 2016 it bought SolarCity, a solar company where Musk was chairman, for about $2.1 billion in stock at closing; the announced equity value had been about $2.6 billion. That deal had no special committee of Tesla’s board, but it was conditioned on a majority of disinterested stockholders, and about 85% of the votes cast by Tesla’s stockholders were in favor. Shareholders sued; Delaware’s courts, applying their strictest test because they assumed Musk was a controller, found the deal “entirely fair,” and the Delaware Supreme Court affirmed in June 2023. Tesla has since moved to Texas, whose 2025 law gives more weight to decisions by independent committees, and Tesla’s bylaws now require a shareholder or group of shareholders to own at least 3% of its shares to bring a derivative suit against directors or officers on the company’s behalf.
In an all-stock deal, the price would be expressed as an exchange ratio between the two companies’ shares. At the Nov 12 closes, one Tesla share was worth about 2.84 SpaceX shares. A premium for Tesla’s shareholders would raise that, and the cost would fall on SpaceX’s.
| Tesla holders’ premium | SpaceX shares per Tesla share (Nov 12 closes) | New SpaceX shares issued (illustration) |
|---|---|---|
| None | 2.84 | about 11.2 billion |
| 20% | 3.41 | about 13.5 billion |
| 30% | 3.69 | about 14.6 billion |
RBC analyst Tom Narayan floated a 20% to 30% premium for Tesla’s shareholders as a scenario in July, Benzinga reported, citing MarketWatch. Nothing about the structure, ratio or premium has been disclosed, and because both prices move daily, any ratio fixed at signing would shift value between the two sets of shareholders until the deal closed.
The roadblocks outside the boardroom
Even an agreed deal would need clearances that have little to do with either board. SpaceX launched 11 of the 12 National Security Space Launch medium- and heavy-lift missions in 2025 and holds security clearances that require arrangements to mitigate foreign ownership, control or influence; its prospectus says some transactions “may be subject to the jurisdiction of” CFIUS, the committee that reviews foreign investment. A combined company would inherit Tesla’s foreign shareholders and its operations abroad, which could reopen those arrangements. SpaceX’s work is also subject to US export controls, which limit what foreign staff, including Tesla’s, could see. Transfers of control of Starlink’s licences would need the consent of the Federal Communications Commission, depending on how a deal were structured.
China is the hardest piece to judge from the record. JPMorgan analyst Rajat Gupta identified Chinese regulatory approval as a hurdle given Tesla’s business there, Investing.com reported, and a Reuters analysis discussed firewalls and data-localisation arrangements; these are opinions, not disclosed conditions.
What each set of shareholders would be weighing
For Tesla’s shareholders, the trade would be exposure for control. They would gain a share of SpaceX’s launch business, its Starlink satellite network and the xAI and X businesses it now owns, and they would lose their one-share-one-vote company. In our illustration, Musk, who directs the votes on 17.7% of Tesla’s outstanding shares, would hold about 75.6% of the combined company’s votes before counting the votes on converted Tesla awards, whose treatment is unknown. Whatever premium the committees negotiated would be the price of that change. Tesla’s shareholders have not always backed Musk-related proposals: in November 2025 an advisory proposal to invest in xAI received more votes for than against but failed because abstentions counted against it; the board had made no recommendation.
For SpaceX’s public shareholders, the trade would run the other way: under the illustrated deal they would gain Tesla’s car and energy businesses, including the China operations discussed in Reuters’ analysis, and see their share of the company diluted by about 11.2 billion new shares or more. All SpaceX shareholders other than Musk held about 17.7% of the votes after the listing, so their votes would not decide the outcome.
For both, the deal would concentrate key-person risk in a single company: one chief executive, one board, one controlling shareholder for businesses that are now separate.
Does it make sense beyond Musk?
There are real overlaps. SpaceX already buys Tesla’s batteries; both companies want large amounts of computing power; and SpaceX now owns an AI developer whose models Tesla’s products could use. Some analysts are enthusiastic: Dan Ives, a partner at Yorkville Ives & Co., puts the chance of a merger by the end of 2027 at 80% to 90%, and estimated that Tesla’s shareholders might need $500 to $550 a share to approve one, CBS reported.
But companies can share batteries, chips and software through contracts, as these two already do, without merging. The sceptics’ point is less about operations than about control. “This package is a distraction from the real story, which is complete control,” Charles Elson, a corporate-governance scholar at the University of Delaware, told Reuters, referring to Musk’s pay in a combined company. Morningstar senior equity analyst Seth Goldstein has raised regulatory questions, including national security, about putting Tesla’s global business together with a company that the US government relies on for launches. Neither company’s committee disclosures address these criticisms.
Seen as a map of interests, the questions are clearer than the answers. Under the illustrated structure, Tesla’s outside holders would gain exposure to SpaceX while entering its dual-class structure; their ordinary vote already needs support beyond Musk, and a separate minority vote would add another check. SpaceX’s existing holders would gain Tesla’s businesses while their share of the company and of the votes was diluted. The government agencies that depend on SpaceX, and regulators in Washington and abroad, will write some of the rules through their reviews. And the founder, whose companies they are, would end up with one company in place of two.
None of that settles whether a merger would be good for either set of shareholders. It shows what the committees have to weigh, and what their shareholders will want to see when, or if, the terms arrive.
What to watch next
- Not dated
- Any announcement from the two special committees: an agreement, its exchange ratio and premium, the fairness opinions, and whether Tesla adds a vote of its shareholders other than Musk.
- Dec 8, 2026
- SpaceX's 180-day IPO lock-up ends; an extended lock-up then releases shares in steps through the release of its second-quarter 2027 results.
- If a deal is signed
- A registration statement (typically a Form S-4) with the proxy for Tesla's vote, and the government reviews: security-clearance arrangements, CFIUS where it applies, export controls and FCC licence transfers.
Quick questions
Have SpaceX and Tesla agreed to merge?
No. Both boards have formed special committees to study a combination, and neither company has announced an agreement or terms. Bloomberg reported on Nov 12, citing people familiar with the matter, that terms and governance were being negotiated; the companies haven't confirmed that.
Who would decide on a SpaceX-Tesla merger?
First the two special committees of independent directors. At Tesla, a deal would then go to a shareholder vote that needs a majority of all outstanding shares, with Musk's shares counting in that vote; the committees could also require a separate vote of the other shareholders. At SpaceX, any approval also needs its controlling shareholder, Musk, who held about 82.3% of the votes after the listing.
How would the price be set?
In an all-stock deal, as an exchange ratio: how many shares of one company each share of the other becomes. At the Nov 12 closes, one Tesla share was worth about 2.84 SpaceX shares with no premium. Any premium for one side's holders would come at the other side's expense. No structure has been disclosed.
About Tesla: Website (external site)Investor relations (external site)SEC filings (external site)Wikipedia (external site)
+ 21 more
Accessed Nov 13, 2026: Tesla: definitive proxy statement, October 2026 (Musk's ownership; xAI and SpaceX ties) · Tesla: certificate of formation (Texas), Exhibit 3.1 (shareholder vote for fundamental business transactions) · Tesla: 8-K on the 2025 annual meeting results, Nov 7, 2025 (xAI investment proposal; derivative-suit bylaw) · Texas Legislature: Senate Bill 29 (2025), enrolled text · Delaware Supreme Court: In re Tesla Motors, Inc. Stockholder Litigation (SolarCity), Jun 6, 2023 · Bloomberg: SpaceX and Tesla talks on a merger are said to progress, Nov 12, 2026 (reported) · NPR: Elon Musk says SpaceX and Tesla are considering a merger, Oct 22, 2026 · Reuters via CNA: Musk's pay under a SpaceX-Tesla merger; voting control (Barclays estimate; Charles Elson), Nov 3, 2026 · Reuters via Investing.com: how a merged SpaceX-Tesla might navigate its China problem (analysis) · Reuters via MarketScreener: Musk keeps Tesla-SpaceX merger speculation alive, July 2026 · Benzinga: RBC's Tesla premium scenario, citing MarketWatch, July 2026 · Investing.com: JPMorgan on Chinese regulatory approval · CBS News: Dan Ives on a potential merger · Morningstar: Seth Goldstein on potential regulatory hurdles · Berger and Ofek: Diversification's effect on firm value, Journal of Financial Economics, 1995 · Berkshire Hathaway: 2014 letter to shareholders (on the conglomerate form) · Alphabet: Larry Page's founders' letter, Aug 10, 2015 · GE: GE completes separation of GE HealthCare, Jan 4, 2023 · GE Aerospace: launch as an independent company after the GE Vernova spin-off, Apr 2, 2024 (Business Wire) · 47 U.S.C. §310(d): FCC consent to transfers of control of licences · Our calculation: Nasdaq.com daily closes for SPCX and TSLA, Jun 12 to Nov 12, 2026, checked against Yahoo Finance and CNBC; share counts from the 10-Qs
Quoting this? You may quote short excerpts under our reuse policy. Please credit WhyMyStockMoved.com and link to this page.